
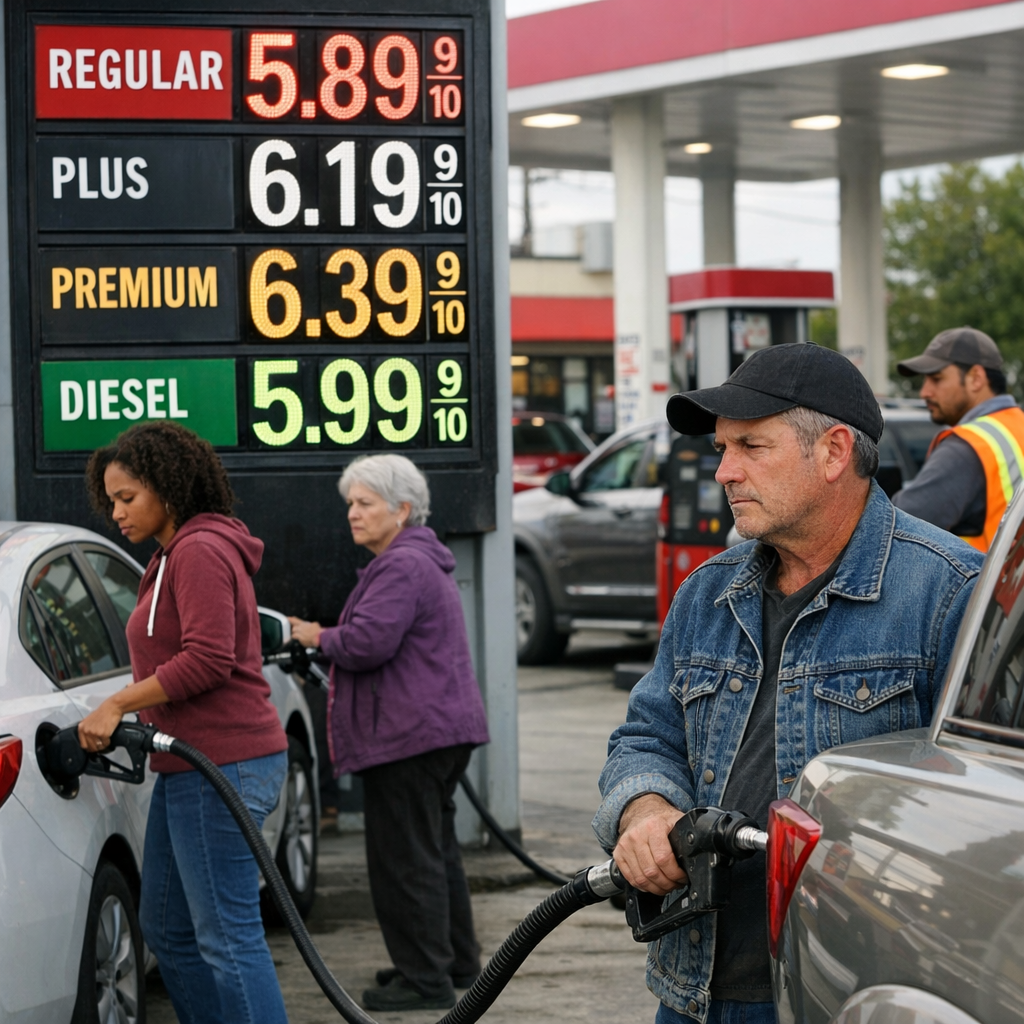
As the nation grapples with economic challenges, many Americans are expressing concerns about rising inflation and escalating energy costs. Recent data indicates a significant increase in consumer prices, with inflation reaching 3.8% in April, the highest in three years. This surge is largely attributed to the ongoing military conflict with Iran, which began in February and has led to the closure of the Strait of Hormuz, a critical passage for global oil shipments. Consequently, average gas prices have exceeded $4.50 per gallon nationally, with some states experiencing prices above $5.
The economic strain is further reflected in public sentiment. A recent CBS News/YouGov poll reveals that 70% of Americans feel “angry” or “frustrated” about the current economic situation. Only 11% expressed enthusiasm, and 19% reported satisfaction. Additionally, 65% of respondents believe that current policies are worsening the economy in the short term, and 50% think they will have a detrimental long-term impact.
In response to these challenges, the International Monetary Fund (IMF) has highlighted the need for cautious fiscal policies. While acknowledging the resilience of the U.S. economy, the IMF warns that rising federal budget debts pose a growing stability risk. The organization projects a 2.4% growth in gross domestic product for the fourth quarter of 2026 but emphasizes the importance of addressing underlying fiscal issues to ensure sustained economic health.
For residents of Simi Valley and across the nation, these developments underscore the importance of staying informed and proactive in managing personal finances. As economic conditions evolve, individuals and communities must adapt to navigate the uncertainties ahead.